

Bridge Report:(3538)WILLPLUS the Fiscal Year ended June 2026

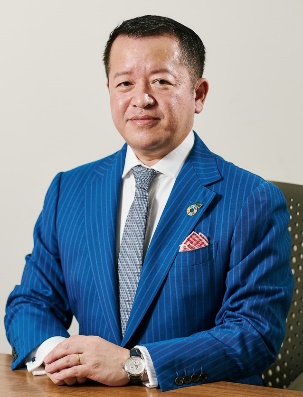 President Takaaki Naruse | WILLPLUS Holdings Corporation (3538) |
 |
Company Information
Market | TSE Standard |
Industry | Retail (Commercial) |
President | Takaaki Naruse |
HQ Address | 5-13-15, Shiba, Minato-ku, Tokyo, Shiba Mita Mori Building 8th Floor |
Year-end | June |
Homepage |
Stock Information
Share Price | Shares Outstanding (Term-end) | Total Market Cap | ROE Act. | ROA Act. | |
¥1,005 | 10,358,400 shares | ¥10,410 million | 9.9% | 3.5% | |
DPS Est. | Dividend Yield Est. | EPS Est. | PER Est. | BPS Act. | PBR Act. |
¥53.67 | 5.3% | ¥138.13 | 7.3x | ¥1,283.99 | 0.8x |
* The share price is the closing price on September 9. From the Brief Report on Financial Results for the fiscal year ended June 2026.
Earnings Trend
Fiscal Year | Sales | Operating Income | Ordinary Income | Net Income | EPS | DPS |
June 2023 Act. | 44,115 | 1,867 | 1,943 | 1,302 | 135.45 | 41.17 |
June 2024 Act. | 47,745 | 1,497 | 1,562 | 1,120 | 116.00 | 43.51 |
June 2025 Act. | 88,614 | 1,849 | 1,897 | 1,443 | 158.43 | 45.06 |
June 2026 Act. | 96,839 | 1,426 | 1,427 | 1,108 | 121.92 | 46.00 |
June 2027 Est. | 116,416 | 2,255 | 2,075 | 1,256 | 138.13 | 53.67 |
*Unit: million yen or yen. Estimates are those of the company. Net income is net income attributable to owners of the parent.
This report includes Willplus Holdings Corporation's financial results for the fiscal year ended June 2026, earnings forecast for the fiscal year ending June 2027, and other information.
Table of Contents
Key Points
1. Company Overview
2. Mid- to Long-Term Strategy
3. Growth Strategy
4. Fiscal Year ended June 2026 Earnings Results
5. Fiscal Year ending June 2027 Earnings Forecasts
6. Conclusions
<Reference: Regarding Corporate Governance>
Key Points
- Willplus Holdings Corporation is a holding company with 9 dealers handling 17 brands of imported cars, including Jeep, BMW, Mini, and Volvo, and a consolidated subsidiary that operate used-car purchase, wholesale, and export. It is actively working to expand its business through an M&A strategy with an aim to acquire "new areas" and "new brand." At the same time, while continuing to "maximize business," the company is also committed to "maximizing GHG emissions reduction" by "greening its stores," seeing "solving climate change issues" as an "opportunity."
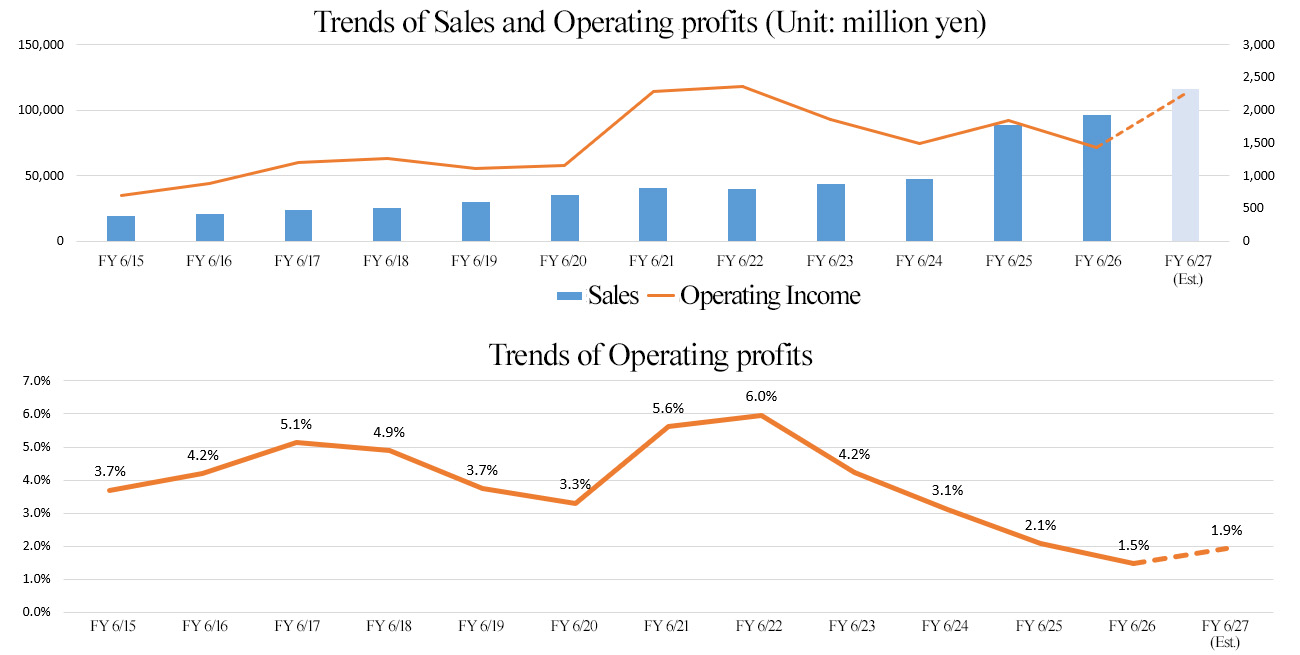
- In the fiscal year ended June 2026, sales grew 9.3% year on year to 96,839 million yen. Despite the harsh business environment, the stores that joined the Willplus Group in the previous fiscal year drove sales. The auto auction sales in the used car export-related business exceeded the forecast. They enhanced sales while putting importance on merchandise turnover. Operating income dropped 22.9% year on year to 1,426 million yen, due to the sluggish sales of new cars and the decline in profitability of used cars in the imported vehicle dealer business, the augmentation of costs due to the increase of stores, the stagnant sales of major models, the rise in procurement costs, the congestion and cost augmentation in maritime transportation in the used car export-related business. Sales and operating income exceeded the revised forecasts announced in May 2026.
- For the fiscal year ending June 2027, sales and profit are expected to grow, while sales will hit a record high. Sales are projected to increase 20.2% year on year to 116,416 million yen and operating income is forecast to rise 58.1% year on year to 2,255 million yen. Only the already announced M&A is taken into account for the earnings forecast. In the fiscal year ending June 2027, too, they will keep conducting M&A, but operating income margin is expected to slowly improve from 1.5% to 1.9%, as “the effect of improvement through post-merger integration (PMI)” will offset “the augmentation of costs through new M&A.” They plan to pay dividends totaling 53.67 yen/share, up 7.67 yen/share from the previous fiscal year. The expected payout ratio is 38.9%.
- While considering the fiscal year ending June 2027 as “the year for earning revenue based on the strengthened organizational capacity,” they will strive to recover the profitability of existing stores and promote PMI for new stores acquired through M&A, with the aim of securing profitability. They will enhance initiatives for human capital-oriented business administration for maximizing the value of human resources, the most important assets of the Willplus Group, and carry out necessary investment for training personnel and improving their organizational capacity. They will keep discussing the necessity of each cost and cost-effectiveness, reduce unnecessary and inefficient costs, and strengthen the management base that enables optimal allocation of managerial resources to growing domains and profitable businesses.
- They actively conduct M&A, which is a pillar of growth strategies. As mentioned in “4. Fiscal Year ended June 2026 Earnings Results [4-5 Topics],” they took over businesses and acquired shares in 7 projects from January to August 2026. The prices of new cars remain high due to the yen depreciation and the inflation. This leads to the augmentation of costs for company-owned vehicles and depreciation, the decrease of visitors to stores, and the worsening of cash management due to the increases in inventory and working capital, weighing on the management of small and medium-sized automobile dealers. In addition, it seems that M&A targeting mainly small and medium-sized dealers whose management bases are weak is accelerating, as people are putting more importance on the response to climate change, high-end automobile makers demand the capital integration among dealers, and imported car dealers are faced with the difficulty in finding successors. Since Willplus Holdings was established in October 2007, they have conducted 13 M&A projects, excluding the ones in less than three fiscal years in the recent past, and all of acquired businesses succeeded in earning profit. Accordingly, their “business revitalization capability” can be said to be remarkable.
- Going forward, the key point will be how PMI can be conducted speedily. They will carry out M&A also in the fiscal year ending June 2027. Operating income margin is expected to improve slowly from 1.5% to 1.9%, thanks to “the improvement effect of PMI” offsetting “the augmentation of costs for new M&A.” Further improvement in profit margin is expected to lead to a rise in PBR through the improvement in ROE.
1. Company Overview
Willplus Holdings Corporation is a holding company with 9 dealers handling 17 brands of imported cars, including Jeep, BMW, Mini, and Volvo, and a consolidated subsidiary that operate used-car purchase, wholesale, and export. It focuses on improving customer satisfaction and pursues growth through a multi-brand strategy, a dominant strategy, and an M&A strategy. It has a significant advantage in business revitalization capabilities in the M&A field. The company aims for further growth, taking the major environmental changes surrounding automobiles, including the shift to EVs, as an opportunity.
[1-1 Corporate History]
In January 1997, the father of President Takaaki Naruse established Sunflower CJ Co., Ltd., an imported car sales company, in Kitakyushu City, Fukuoka Prefecture. The company was the first official Chrysler dealer in western Japan.
In October 2004, President Naruse acquired all of the company's shares and started business activities as the Willplus Group.
Although it was a small dealer with a few staff members, including President Naruse, it achieved excellent results nationwide in sales of Chrysler cars and received high acclaim, which led him in 2005 to take over Chrysler's directly managed store in Ohta-ku, Tokyo, and advance to Tokyo. In 2006, the company opened a store in Kurume City, Fukuoka Prefecture. It also started a dominant strategy in Tokyo and Fukuoka.
Willplus Holdings Corporation was established in October 2007 to flexibly acquire dealers through optimal allocation of management resources and prompt management decision-making.
Under the holding company structure, the company actively expanded its business scope and was listed on the JASDAQ of the Tokyo Stock Exchange in March 2016. In September 2017, as the market changed, it shifted to the Second Section of the Tokyo Stock Exchange, and then it was listed on the First Section of the Tokyo Stock Exchange in February 2018. The company got listed on the Prime Market of Tokyo Stock Exchange in April 2022 in step with the market restructuring, and then listed on the Standard Market in October 2023.
[1-2 Corporate Philosophy]
In this section, we state the company's significance and core values.
Our Significance (MISSION STATEMENT) We propose a life with imported cars, share affluence, fun, and joy with more people, and continue to take on the challenge of drawing warm smiles on the face of everyone involved. |
Core Values ・Love our cars, love our colleagues, and work with pride. ・Always take on challenges and break through our limits. ・Achieve great results through teamwork. ・Make sure we reach our goal on time. ・Never give up until the end, and do our best. ・Provide richness, enjoyment, and joy. ・Never forget to be sincere and grateful. |
[1-3 Market Environment]
The business environment, which is essential in understanding the company, is as follows.
Regarding the business environment related to the M&A strategy, which is the company's growth driver, see “2. Mid- to Long-Term Strategy”.
◎ The share of imported cars in the domestic passenger car market continues to increase, and the number of imported cars owned in Japan is growing steadily.
The number of new cars registered in Japan shows a decreasing trend due to the declining birth rates and aging population, the prolongation of the period of owning a car due to the elevation of functionality, changes in consumption styles and preferences (decrease of young people who own automobiles), etc.
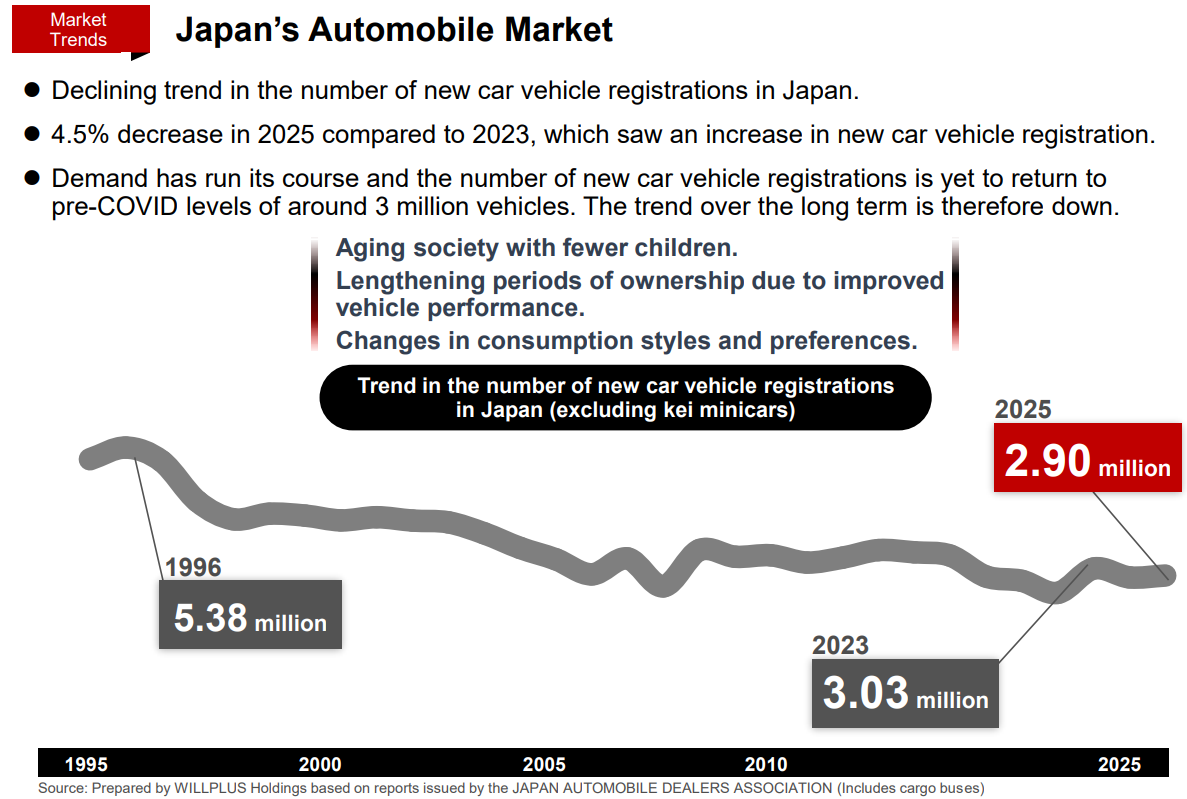
(From the reference material of the company)
Against this backdrop, the recovery of the domestic imported vehicle market has been sluggish due to the rise in new car prices due to exchange rate fluctuations and inflation. However, the market share of imported vehicle registrations increased 0.5 percentage points year on year in 2025. In the long term, the market share of imported vehicle registrations is increasing.
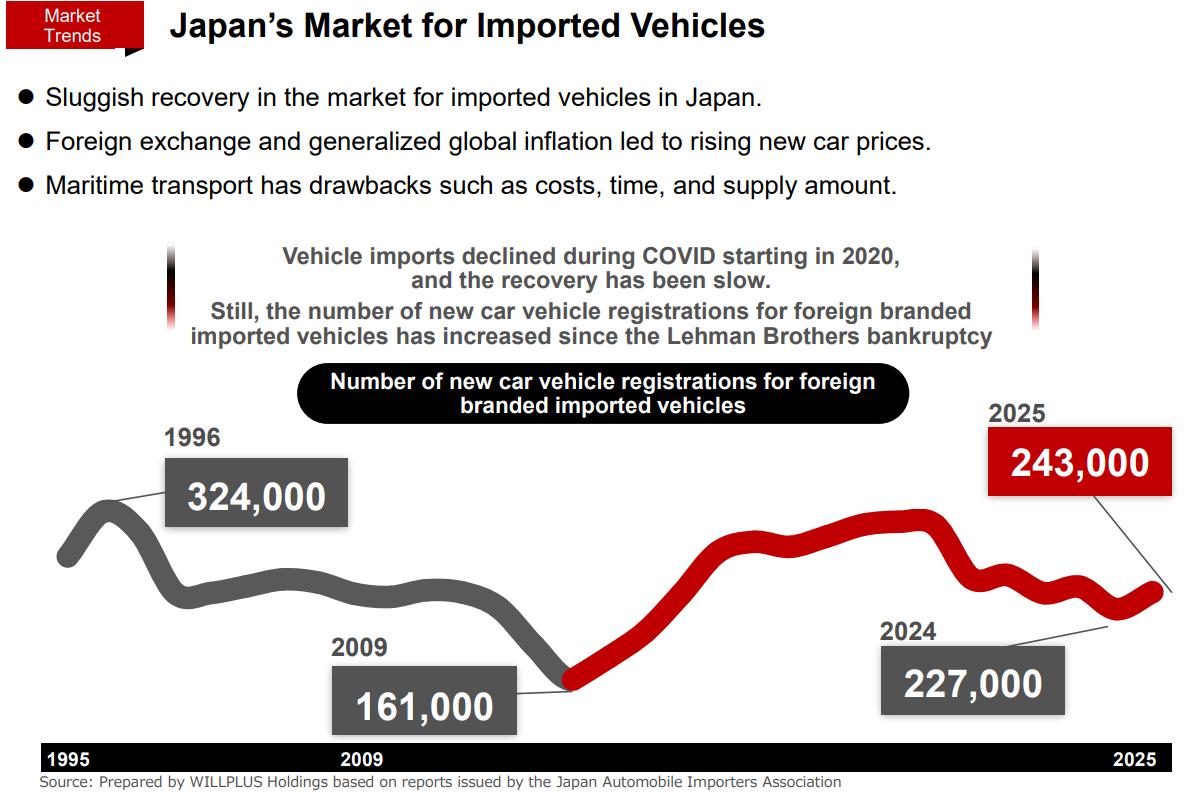 |
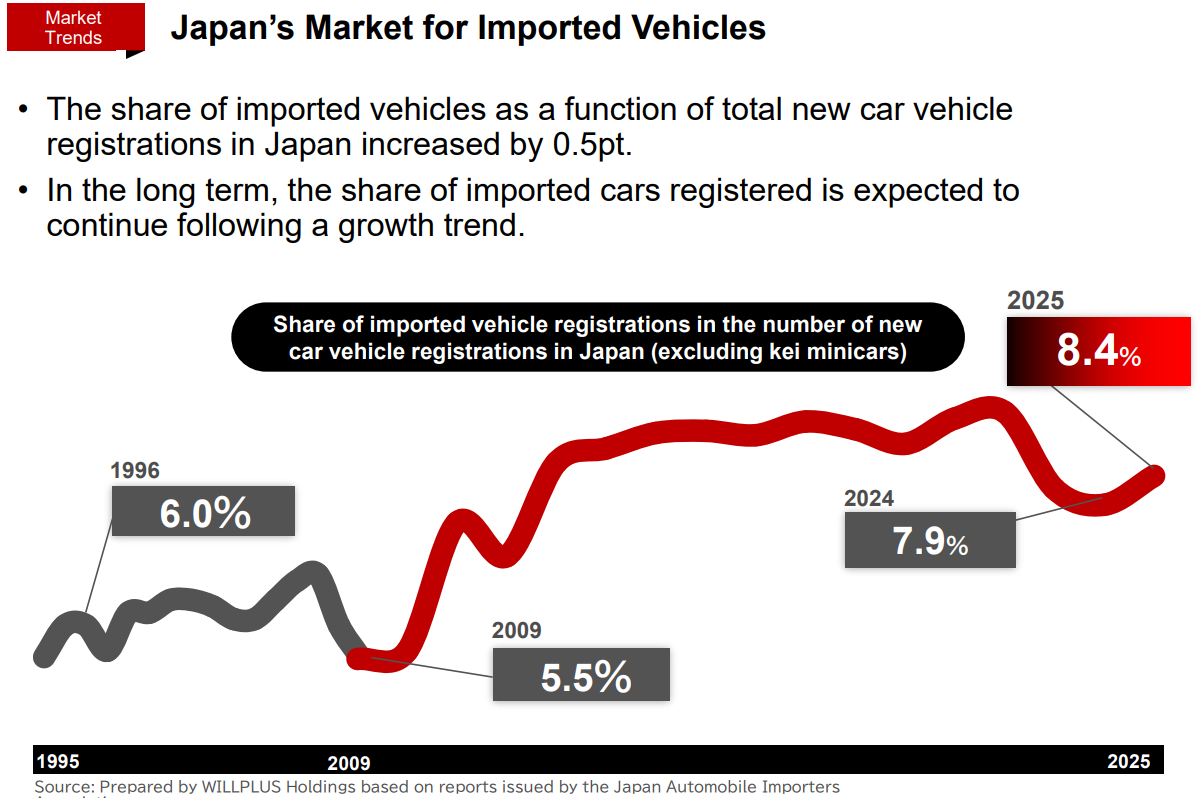 |
(From the reference material of the company)
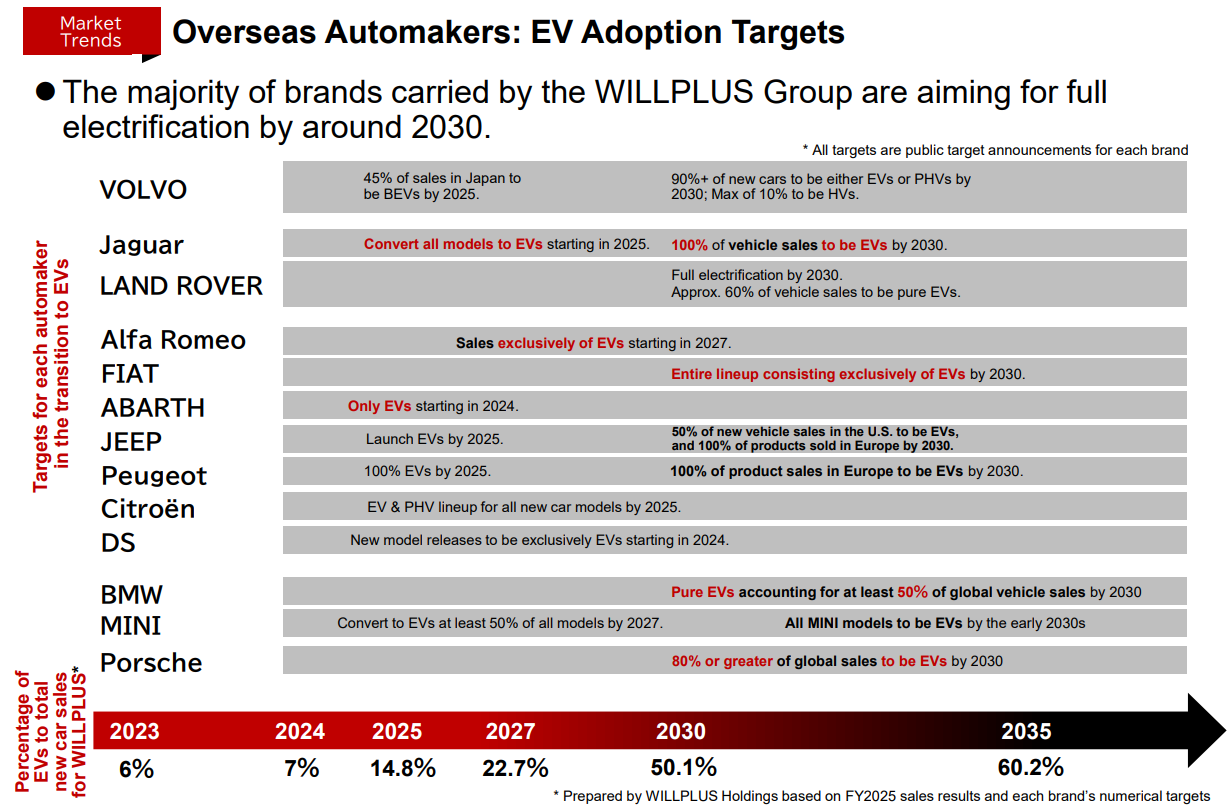
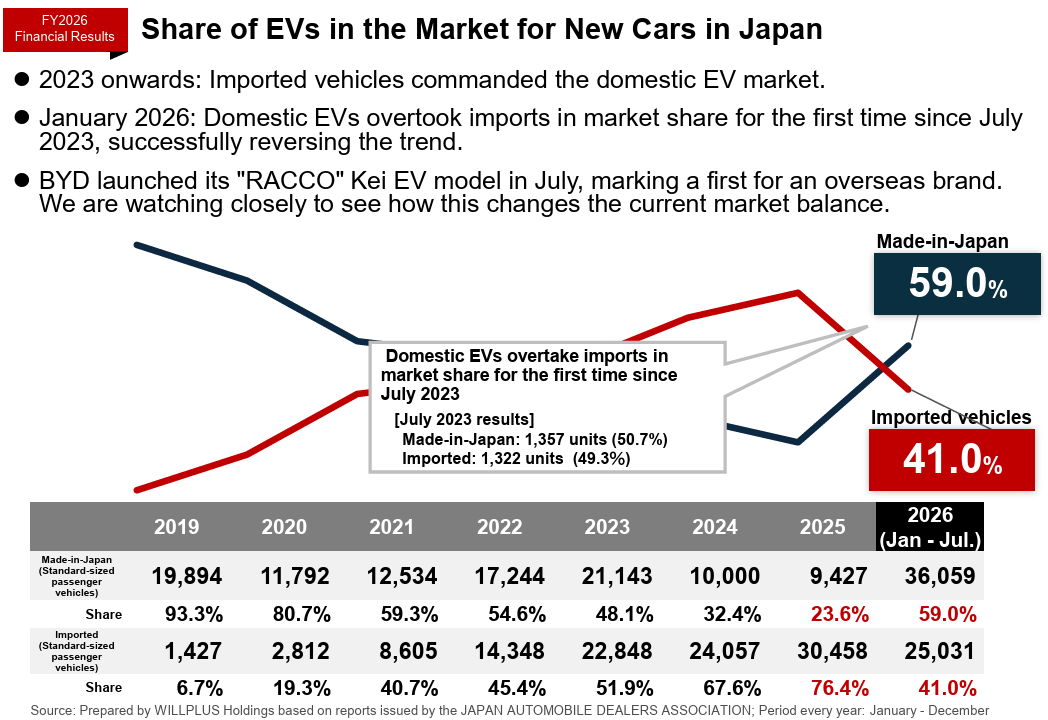
The imported car manufacturers are proactively addressing environmental issues and the majority of brands in which the company deals have announced plans aiming for complete electrification by 2030. On the other hand, the expansion pace for Japanese manufacturers' EVs has been slower than overseas competitors; however, in January 2026, the share of domestically produced EVs in the domestic new car market exceeded that of imported vehicles. This is the first time since July 2023. The revitalization of the domestic EV market is expected to lead to the expansion of infrastructure.
 |
 |
(From the reference material of the company)
◎ Comparison with other companies in the same industry
Code | Company | Sales | Sales growth rate | Operating income | Profit growth rate | Operating income margin | ROE | Market Capitalization | PER | PBR |
3184 | ICDAHLD | 39,500 | 1.4 | 2,051 | 5.1 | 5.2% | 11.5 | 8,725 | 6.5 | 0.7 |
3538 | Willplus HLD | 116,416 | 20.2 | 2,255 | 58.1 | 1.9% | 9.9 | 10,410 | 7.3 | 0.8 |
7593 | VT HLD | 400,000 | 2.9 | 13,500 | 22.7 | 3.4% | 6.9 | 64,355 | 8.7 | 0.9 |
8291 | Nissan Tokyo Sales HLD | 140,000 | 8.5 | 6,000 | 26.1 | 4.3% | 4.7 | 32,470 | 9.3 | 0.6 |
9856 | KU HLD | 170,000 | 0.5 | 8,100 | -3.3 | 4.8% | 8.4 | 53,657 | 6.8 | 0.6 |
* Units: million yen and %. Sales and operating income are company forecasts for this term. ROE is the result of the previous fiscal year. Market capitalization is the number of shares at the end of the most recent quarter × the closing price on September 9, 2026. PER (forecasted figures) and PBR (actual figures) are based on the closing price on September 9, 2026 (The figures of ICDAHD are based on the closing price on September 7).
PBR remains below 1 with PER being single-digit. The company expects to make steady progress with the measured mentioned in “2-5 Measures for Achieving Management Focusing on Capital Costs and Stock Prices.”
[1-4 Business Description]
(1) Overview
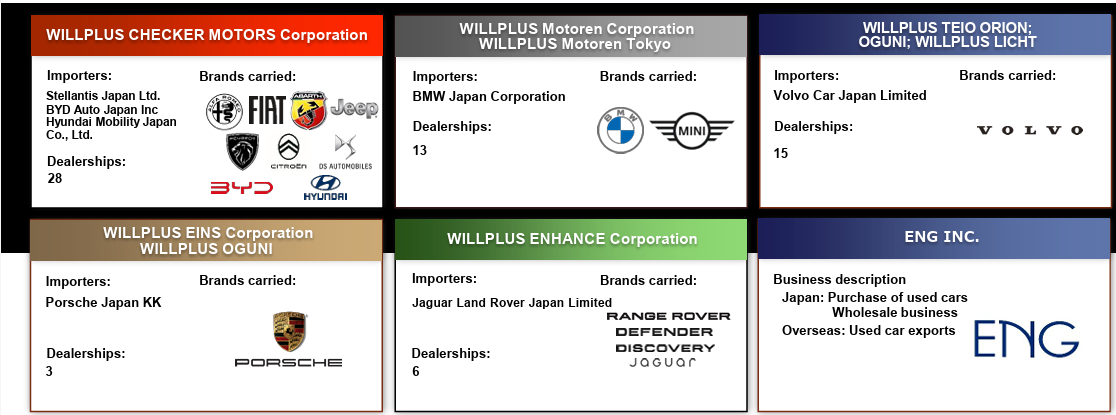
Under the holding company Willplus Holdings Corporation, 10 consolidated subsidiaries engage in sales of imported new and used cars, vehicle maintenance, non-life insurance agency business, and used-car export. The company handles 17 brands. The company has an official dealer contract with an importer (a company that handles imported cars in Japan) for each brand it handles.
(From the reference material of the company)
(2) Segments
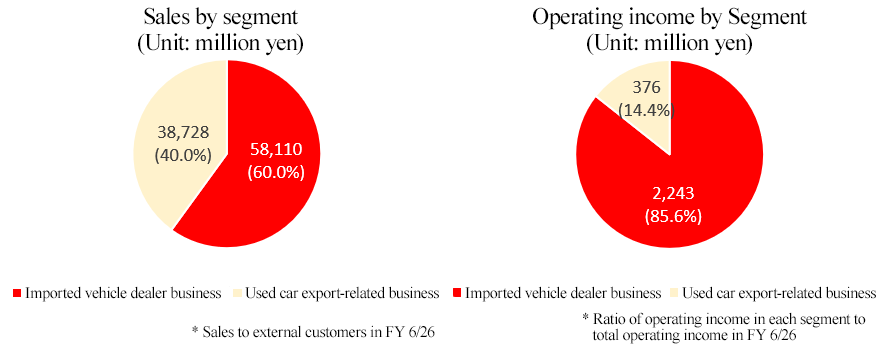
There are two segments to be reported: the imported vehicle dealer business and the used car export-related business.
(3) Products and services (business description)
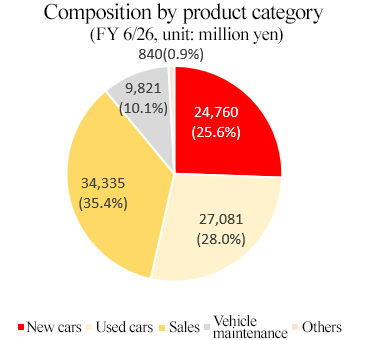
The company discloses sales classified into the categories of new cars, used cars, auto auction sales, vehicle maintenance and other services in the summary of financial results. The company also discloses the domestic and overseas breakdowns of used car sales.
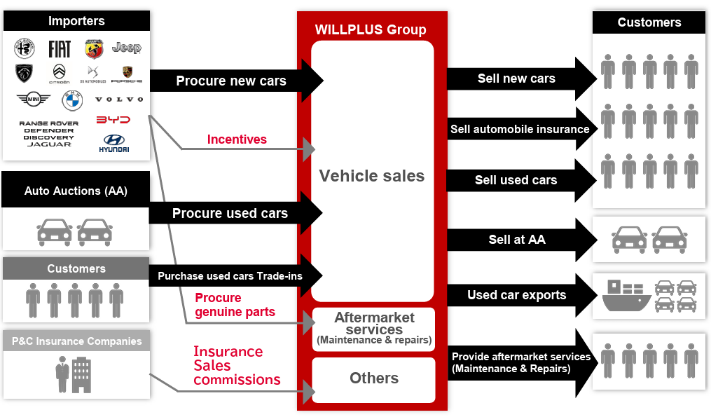
(From the reference material of the company)
Products and Services | Description |
|
New cars | As authorized dealers, the companies sell all new car brands procured from each importer. | |
Used cars | It mainly sells certified used cars of recent models of each brand with a short travel distance. Products are purchased through trade-ins at the time of selling new cars, purchases, and automobile auctions. ENG INC. exports used cars purchased in Japan mainly to Malaysia. | |
Sales | It sells trade-in used cars of other brands at automobile auctions. In addition, at the request of dealers of other companies, it may sell new and used vehicles owned by the corporate group. | |
Vehicle maintenance | The main services are maintenance, repair, and inspection of the sold vehicles. With the exception of some stores, service centers are set up alongside showrooms. | |
Others | It sells compulsory automobile liability insurance and voluntary insurance as an agent for non-life insurance companies. Incentive income related to new car sales from importers is also included. |
Although the sale of new cars is the main business. The company is focusing on the sale of used cars and strengthening customer relationships by providing services that customers need after purchasing a car, such as vehicle maintenance and car insurance sales.
Regarding vehicle maintenance, maintenance packages are provided to ensure maintenance after sale. As for insurance sales, the provision of detailed information on insurance products has been highly evaluated, and the enrollment and retention rates are higher than the industry average.
In addition to “the increase in the number of units sold = the increase in one-shot revenue,” an increase in the number of stores through M&A has led to an increase in recurring revenue in the form of “increase in the number of car maintenance and insurance contracts.”
Additionally, the inclusion of the "used car export-related business" in the business portfolio has enabled the company to enter a growing market and mitigate foreign exchange risk on a group-wide basis.
(4) Number of stores
As of the end of August 2026, the number of stores is 28 in Tokyo, Kanagawa and Saitama, 25 in Kyushu, 3 in Shikoku, 3 in Hyogo, 2 in Yamaguchi, 2 in Miyagi, and 2 in Fukushima, for a total of 65 stores.
[1-5 Characteristics, Strengths, and Competitive Advantages]
(1) Advanced capability to revitalize business through M&A
From the perspective of "purchasing time," many companies currently use M&A as a pillar of their growth strategies. It goes without saying that finding excellent deals and executing them at appropriate prices are essential for a successful M&A. However, the post-M&A process called PMI (Post Merger Integration) to create the expected synergy effect is seen as more important. There are countless cases of M&A failing due to a lack of prior assessment of factors that impede integration and the inability to manage differences in corporate culture.
Under such circumstances, investors should pay attention to the company's business revitalization ability. Since the establishment of Willplus Holdings in October 2007, the company has carried out 13 M&A deals to date. All deals have turned profitable. *Excluding those conducted less than last three fiscal years.
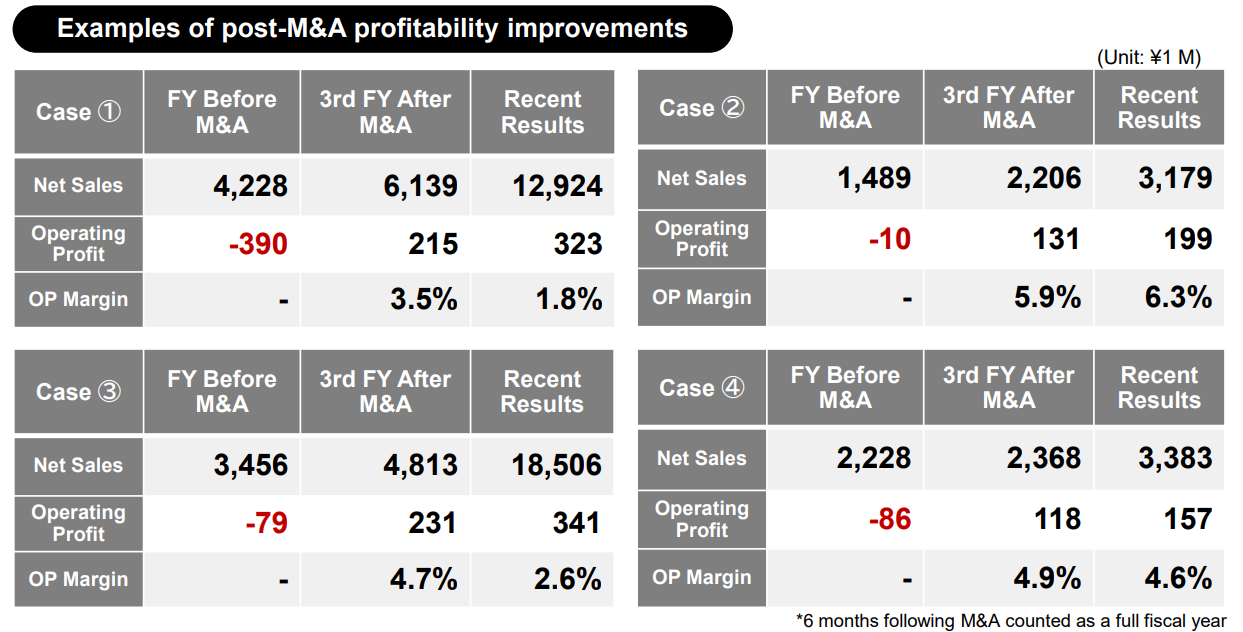
(From the reference material of the company)
The key to a successful M&A is sharing philosophies, such as pursuing the improvement of customer satisfaction and clarifying the evaluation criteria, which includes respecting challenges to the maximum extent possible. The company believes these key factors can drastically change companies and has great confidence in its ability to revitalize its business.
(2) The only listed company whose main business is being an authorized dealer of imported cars
While there are many companies that are authorized dealers of imported cars while mainly relying on selling used cars, the company is the only listed company that mainly sells new cars.
The company estimates that the scale of the new imported car market will reach 1.75 trillion yen in 2025. Believing that the share of imported cars in the domestic passenger car market (excluding mini cars) shows an increasing trend in the long term, the company intends to pursue further growth of revenues by expanding their market share based on an M&A strategy.
(3) Stable revenue structure based on the recurring revenue business
The stable revenue structure based on car maintenance and insurance sales, which are recognized as recurring revenue businesses, represents another significant characteristic and forte of the company.
The sum of car maintenance and insurance sales commissions has been growing for ten consecutive years since the company became publicly listed, reaching a new record high, partly due to M&A.
While a significant increase of owned cars in Japan can hardly be expected, a rising trend can be seen in the average number of years of using a car due to the changes in the economic situation, elevation of awareness concerning the environment, etc., inevitably making maintenance more important.
In addition, with the development of “CASE,” maintenance work is expected to become more complex, and maintenance work for imported vehicles is expected to be concentrated at authorized dealers.
Given these factors, the company believes that opportunities for earnings in the vehicle maintenance business will continue to increase, and it will seek to strengthen the foundation of this business by increasing the percentage of vehicles that come in for maintenance by adding maintenance packages and extended warranties for new vehicles.
In addition, the company will continue to brush up its staff's insurance knowledge to further improve customer satisfaction with regard to insurance commission income, which has been growing every fiscal year, and further strengthen the foundation for stable growth in the recurring revenue businesses of insurance sales and vehicle maintenance.
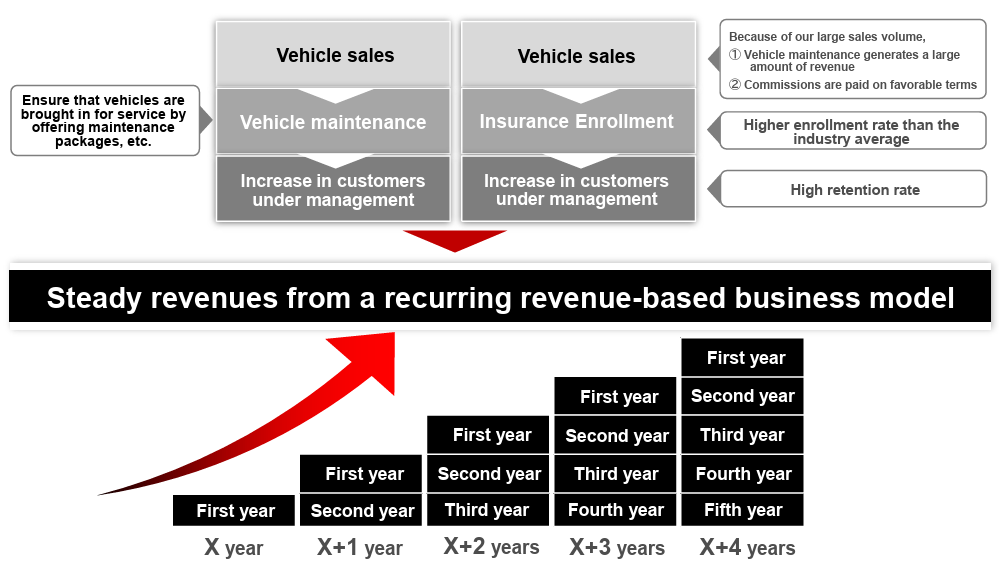
(From the reference material of the company)
2. Mid- to Long-Term Strategy
While today’s companies are required to improve their social significance and corporate value to solve social issues, the company formulated and implemented a mid- to long-term strategy based on its basic growth strategies (multi-brand strategy, dominant strategy, M&A strategy).
[2-1 Willplus Group Policy Regarding Mid- to Long-Term Strategy]
The company aims to enhance social value and corporate value. In other words, the company aspires to solve social issues and achieve corporate growth.
The company will strive to “contribute to the realization of a sustainable society” and “create social value” as a step toward the elevation of their social value.
Concretely, they will forge ahead with making their stores greener and decarbonizing the store areas, aiming for an enterprise that is needed by society.
They aim for “sustainable growth” and “elevation of corporate value in the medium- to long-term” as a step toward the elevation of their corporate value.
Concretely, they will promote their growth strategy, centered on M&A, and engage in solving issues through corporate revitalization in the car sales industry, where many small and medium-sized enterprises exist, by resolving the challenge of finding a successor, reusing assets (resources), improving profitability, and reeducating and stimulating human resources (human capital) while aiming for the maximization of sales and profit, as described below.
They view “the solving of issues concerning climate change” as an “opportunity,” aim for “dominating,” “expanding areas,” and “acquiring new brands,” make proactive efforts to expand their business through “M&A” and work toward the “maximization of market capitalization” through the elevation of their social value and corporate value.
[2-2 Goal]
As the commitment to issues concerning climate change including the supply chain is sought, brand manufacturers are starting to demand the accurate grasping of GHG emissions from store operation, setting of goals for the reduction of GHG emissions and concrete initiatives to achieve these goals (ratio of EVs among demo cars, ratio of renewable energy use, ratio of recycled waste, etc.) from official dealers.
The company, which aims to be a leading company in solving climate change issues, has set the following GHG emission reduction targets.
To reduce Scope 1 + Scope 2 GHG emissions by 50% in FY 2030 compared to FY 2022 (6.25% reduction per year).
Concretely, they set goals of
①increasing the ratio of low-carbon vehicles to company vehicles (including test-vehicles) to 80% or higher by FY 2030”
②adopting renewable energy at all stores by FY 2025
In March 2026, we obtained a third-party assurance on their GHG emissions in FY 2025.
Regarding Scope 2, we have continued to achieve zero emissions by switching to renewable energy contracts and utilizing green certificates.
In FY 2025, the company has achieved a 26.8% reduction in emission levels compared to FY 2023, when the group target was achieved ahead of schedule.
[2-3 Initiatives of the Willplus Group]
The company’s initiatives for realizing “the elevation of social value” and “elevation of corporate value” at the same time are outlined below.
(1) Social Value Enhancement
① Contribute to the realization of a decarbonized society by promoting green store operations
In addition to setting the above reduction targets, the company intends to make capital investments to promote the spread of EVs in its store areas as an imported car dealer striving to be one of the first to promote green store operations, thereby contributing to the decarbonization of the domestic automobile industry.
The achievements they have made so far are as follows.
 |
|
(From the reference material of the company)
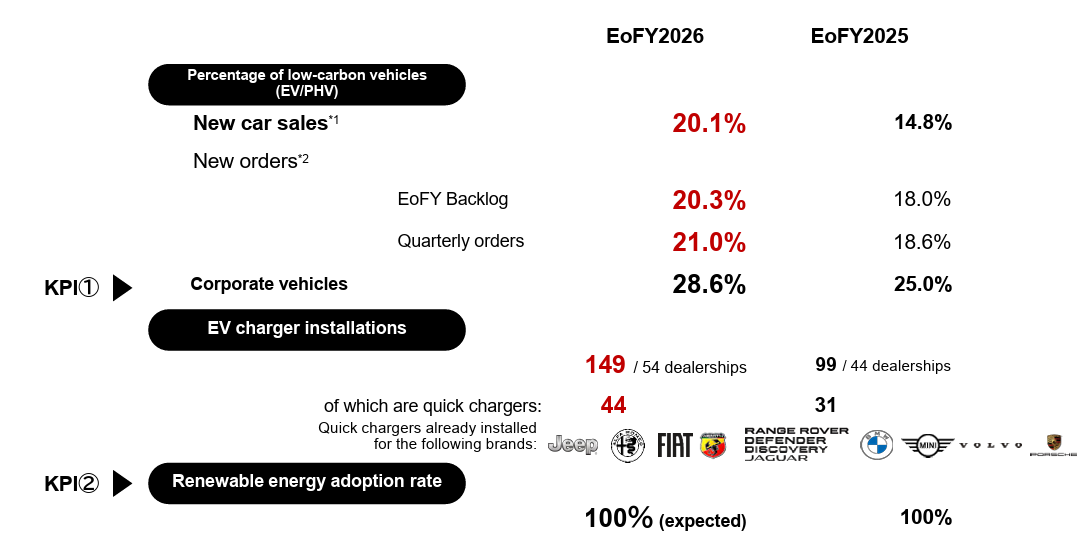
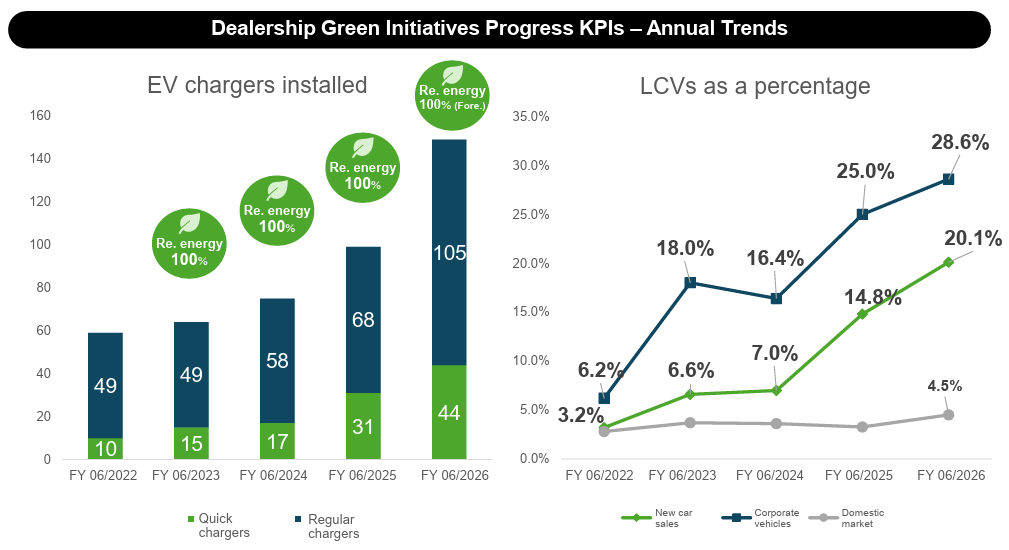
The number of EV chargers installed is increasing in parallel with the expansion of the EV lineup of the brands handled by the company. As of the end of June 2026, a total of 149 units have been installed, including 44 rapid chargers and 105 standard chargers. Renewable energy rate reached 100% for the fourth consecutive year.
In the fiscal year ended June 2026, low-carbon vehicles accounted for 20.1% of new cars sold and 28.6% of company-owned vehicles, showing a steady increase.
② Other Initiatives and Responses
◎ Obtained the score B in the CDP “Climate Change” questionnaire for four consecutive years
In response to requests from institutional investors and purchasing companies around the world, the company answered the questionnaire regarding climate change conducted by the international organization Carbon Disclosure Project (CDP), which promotes companies to disclose environmental information, and obtained Score B for four consecutive years (2022, 2023, 2024, and 2025).
The CDP questionnaire is aimed at evaluating each organization’s disclosure of environmental information with the grades A to F as a global standard regarding “E” of ESG (environment, society, and governance). As of 2025, 22,000 companies, which account for over two thirds of the global market cap, were scored by CDP, and institutional investors and purchasing companies around the world refer to such information when making decisions. In Japan, about 2,100 companies, including over 1,000 companies listed on the Prime Market, answered the questionnaire.
(2) Enhancement of corporate value through promotion of M&A
M&A is an important measure for quickly entering new areas, acquiring new brands, and expanding the market shares of existing brands. In the saturated domestic automobile market, the company believes that M&A is the most appropriate and priority strategy from the perspectives of customer acquisition, early return on investment, and securing profits.
Armed with the "advanced capability to revitalize business through M&A" mentioned in [1-5 Characteristics, Strengths, and Competitive Advantages,] they will strive to expand their sales and profit through M&A and steady PMI.
① Business Environment for M&A Promotion
◎ Dealer Status
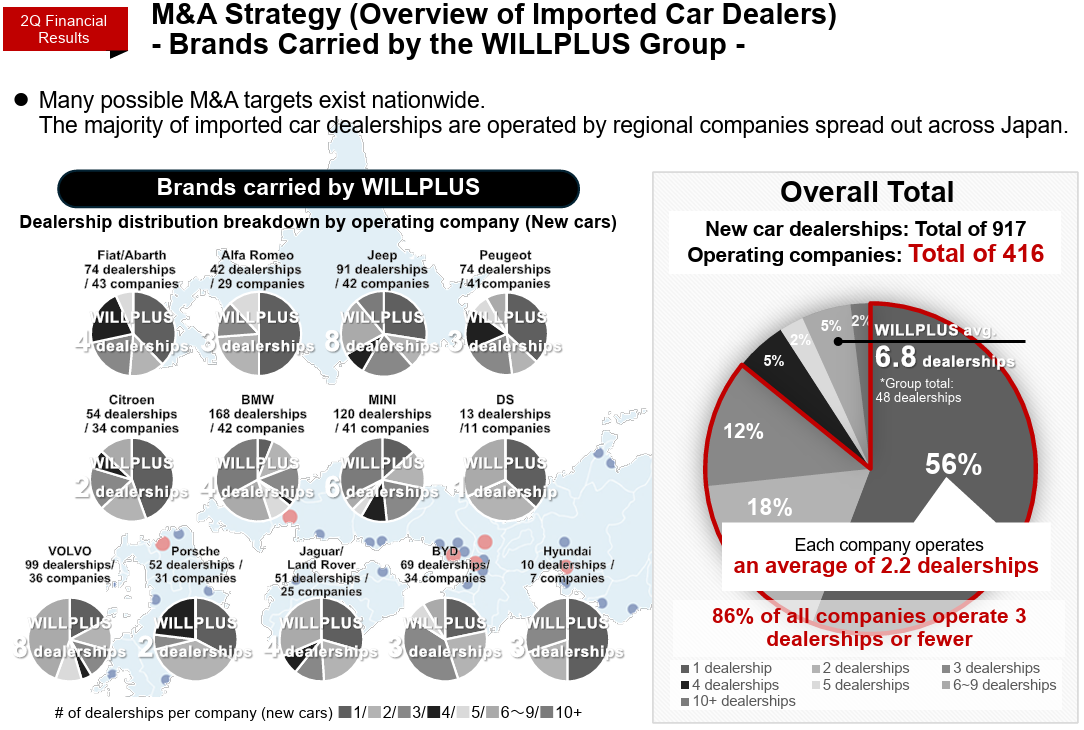
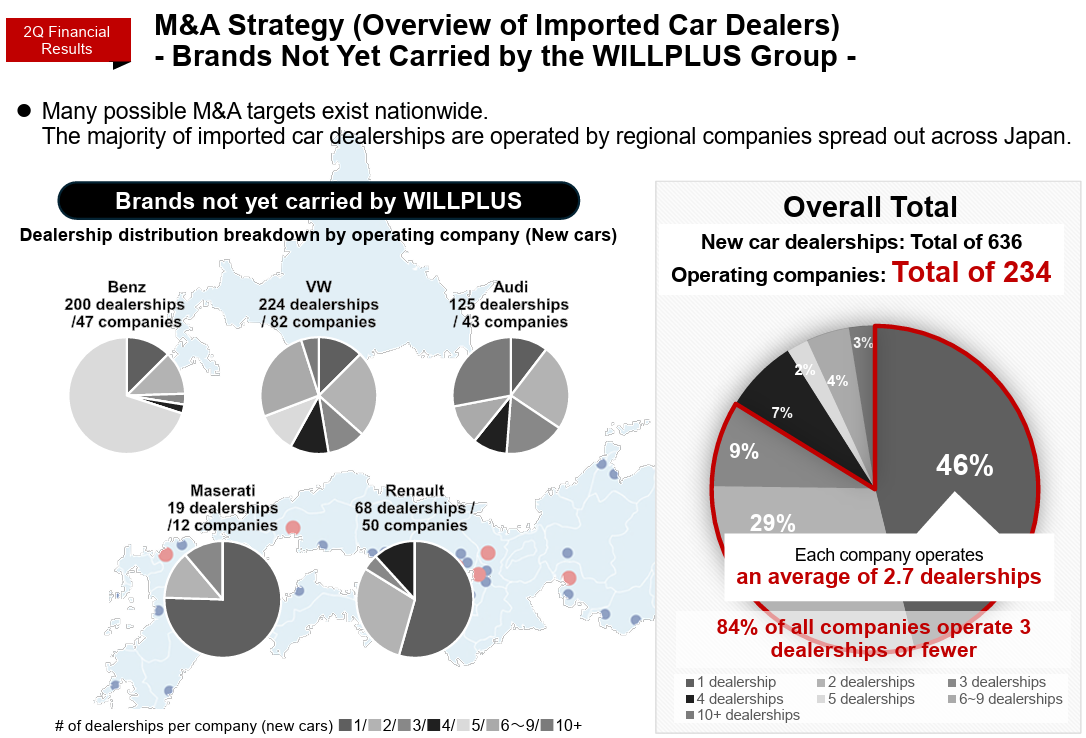
According to the company's assessment of brands, there will be a total of 650 imported automobile dealers operating throughout Japan by the end of 2025, with a total of 1,553 new car sales offices. Each company had an average of 2.4 shops, while small and medium-sized businesses with three or fewer shops accounted for approx. 80% of the total number of dealers.
Store operation varies from brand to brand, and some brands are consolidating capital.
In addition, many dealers are struggling with the difficulty in finding successors, a common problem for small and medium-sized companies in Japan.
 |
 |
(From the reference material of the company)
For these imported car dealers, the "CASE" of automobiles, of which "Electric Vehicle" and "Connected" are the most important management issues for the future.
* "CASE" stands for Connected, Autonomous, Shared & Services (which may refer to car sharing and services/sharing only), and Electric. They are drastically changing the conventional concept of a "car" and creating new demand and markets in each of these areas.
◎ Enhanced Environmental Awareness and the Progress of the Shift to EVs
With heightened awareness of the global warming crisis, efforts to reduce greenhouse gas emissions and realize a decarbonized society are progressing rapidly.
One of the most significant concerns is reducing automotive emissions, and as governments try to attain carbon neutrality by 2050, automobile manufacturers are shifting from traditional gasoline and diesel engine cars to electric vehicles (EVs) in order to survive.
As mentioned in [1-3 Market Environment], manufacturers headquartered in Europe, which has long had a high degree of environmental awareness, have been particularly engaged in the transition to EVs.
On the other hand, while Japanese manufacturers set targets for the number and ratio of sold EVs, the expansion pace is sluggish in comparison with overseas competitors.
At the same time, brand car manufacturers must commit to developing a firm understanding of emissions throughout their supply chains and to reducing them, so they are increasingly urging dealers to not only understand their current emissions, but also to make appropriate capital investments and responses to climate change issues, such as increasing EV purchases, installing quick chargers, and disclosing emission reduction targets.
Many dealers, however, face financial and human resource limits that make it difficult for them to respond adequately, and some analysts predict that brand car manufacturers may take the lead in further combining and restructuring vendors who can respond appropriately to such demand.
◎ Complication of car maintenance through the spread of connected systems and EVs
The term "connected" refers to the usage of communication equipment in automobiles to enable continuous external contact. Equipping vehicles with a SIM card will allow for grasping the state of a car and the situation on a road, exchange of information between cars and between a car and infrastructure, remote control, etc.
The connected automobile will evolve into smartphone-like devices, improving convenience while potentially complicating maintenance work in the case of a breakdown or vehicle inspection.
Furthermore, the previously noted shift to EVs will have a significant influence on car maintenance. Through the distribution of EVs, high-voltage battery and generator failures will increase, and vehicle maintenance will need to manage high-voltage systems, prompting substantial investment in high-voltage equipment and special training for safety reasons. Because the shift to connected systems and electric cars will need greater investment in both hardware and software, maintenance work for imported vehicles is likely to be concentrated in the hands of authorized dealers and large capital organizations with substantial investment capacity.
② The company's policy on M&A
◎ Actively addressing climate change issues
While responding to EVs and connected automobile is an urgent task for imported car dealers, the company intends to differentiate itself by building stores that are preferred by brand car manufacturers and by acquiring dealers who find it challenging to address these issues through M&A. By doing so, it hopes to expand into new areas and pick up new brands in order to grow and boost its corporate value. Additionally, the company wants to help with social issues by creating new brands and working to make its stores greener.
The company will not only decarbonize the neighboring area and turn the stores green, but it will also reinvigorate the social capital that already exists by repurposing resources and assets including stores, retraining personnel, and enhancing productivity by streamlining processes using DX.
◎ Favorable M&A Conditions after the subsiding of COVID-19
The company believes that the M&A strategy is beginning to receive a tailwind as COVID-19 is coming to an end.
*2020-2022: Business environment in which M&A (sale of business) is unlikely to be conducted
In the wake of the outbreak and spread of COVID-19, the demand for automobiles as a safe transportation means or for domestic travel as an alternative to overseas travel grew rapidly from 2020 to 2021.
In 2022, the prices of new automobiles skyrocketed due to the shortage of supply caused by the global shortage of semiconductors and the rise in material prices, and the shortage of new automobiles led to the growth of demand for used automobiles, and the prices of used automobiles rose significantly.
In such business environment, the sale and order receipt of automobile dealers were healthy. Inventory declined, working capital shrank, and order backlog increased steeply, so even dealers with weak marketing capabilities and small capital stock were able to operate business without trouble.
On the other hand, dealers thinking of selling their businesses decreased in that situation. It was unfavorable for the M&A strategy of the company, but the company’s growth and operating income margin exceeded the average in the industry, and the company concentrated managerial resources onto M&A in the next phase.
* Since 2023: Acceleration of M&A in parallel with the recovery of supply of new automobiles
Since 2023, the above environment has undergone some changes.
Although the supply of new vehicles is recovering as the pandemic subsides and the semiconductor shortage eases, persistently high prices of new cars, driven by the yen depreciation and inflation, are putting pressure on the operations of small and medium-sized auto dealers. These dealers are facing increased costs resulting from higher investments in company-owned vehicles and higher depreciation expenses, a decline in customer visits, and worsening cash flow due to rising sales inventory and working capital requirements.
Additionally, as the focus on addressing climate change increases and automakers seek to consolidate dealerships, coupled with the shortage of successors at import car dealerships, M&A deals are expected to increase, especially among small and medium-sized dealerships with fragile financial foundations. Under the business environment where M&A is easily accelerated, M&A has started accelerating after three-year stagnation. The company plans to allocate its management resources toward M&A activities to stimulate business growth.
[2-4 Medium- to Long-term Shareholder Return Strategy]
The company, which has increased dividends consecutively since its listing, has established the following policy.
☆ | To target a medium- to long-term ROE of 15% or higher (9.9% in the fiscal year ended June 2026). |
☆ | In order to "keep sufficient capital" and "further boost shareholder return," they set a target payout ratio of 30% or higher in the fiscal year ended June 2026. |
☆ | From the fiscal year 2027 onward, the company will continue to pursue a dividend policy of pursuing a payout ratio of 30% while aiming for progressive dividends. |
☆ | The company will sustain and increase consistent and ongoing returns to shareholders, with a DOE of 4.5% or higher. |
They plan to pay dividends totaling 53.67 yen/share, up 7.67 yen/share from the previous fiscal year. The expected payout ratio is 38.9%.
In order to demonstrate its extremely aggressive profit growth policy and shareholder return stance, the company aims to achieve ROE that significantly exceeds the cost of shareholders' equity, increase the dividend payout ratio gradually, and increase dividends in excess of profit growth.
(ROE Analysis)
| FY 6/18 | FY 6/19 | FY 6/20 | FY 6/21 | FY 6/22 | FY 6/23 | FY 6/24 | FY 6/25 | FY 6/26 |
ROE (%) | 18.2 | 14.3 | 13.9 | 22.5 | 19.0 | 14.0 | 11.5 | 14.0 | 9.9 |
Net income margin (%) | 3.16 | 2.44 | 2.29 | 3.76 | 3.91 | 2.95 | 2.35 | 1.63 | 1.14 |
Total asset turnover (times) | 2.49 | 2.30 | 2.24 | 2.43 | 2.23 | 2.09 | 1.71 | 2.55 | 2.39 |
Leverage (x) | 2.31 | 2.54 | 2.71 | 2.46 | 2.18 | 2.28 | 2.85 | 3.37 | 3.61 |
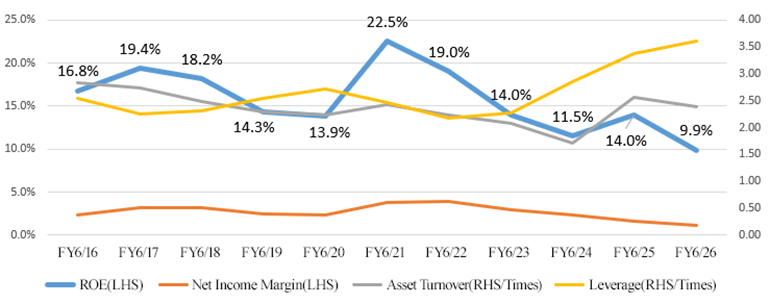
Although it exceeds 8%, which is generally considered as a target for Japanese companies, it is declining. We would like to expect that ROE will rise and PBR will recover to the level of 1x, through the improvement in profitability.
[2-5 Measures for Achieving Management Focusing on Capital Costs and Stock Prices]
Regarding the “Measures for Achieving Management Focusing on Capital Costs and Stock Prices” requested by the Tokyo Stock Exchange, the company has presented the following analysis and future initiatives. (The updated information was disclosed in August 2026.)
(1) Analysis of the Current Situation
(Stock Price)
While the supply of new cars has recovered after the COVID-19 pandemic, car prices have remained high due to the weak yen. As the overall imported car market has been sluggish, ROE has declined due to deteriorating business performance. As a result, stock price has been low, with PBR less than 1x despite the support of dividend yield.
(Trends in Sales and New Store Openings After Listing)
During periods of strong business performance (FY 2021 and FY 2022), no M&A transactions were made. From FY 2023, business performance declined due to the deterioration of the imported car market, but M&A increased rapidly. However, stock price does not represent the outcome of M&A (sales growth). The company acknowledges that "profit improvement through PMI" is required to mitigate the effects of the declining imported car market.
(ROE and PBR)
The company acknowledges its cost of equity as 5.49% based on the CAPM, and ROE has been exceeding the capital cost since the company’s public listing. However, in the fiscal year ended June 2026, ROE decreased to 9.9%, as profit was sluggish due to the worsening of the market environment and the upfront costs for active M&A. PBR, too, dropped significantly.
(2) Initiatives to Improve PBR
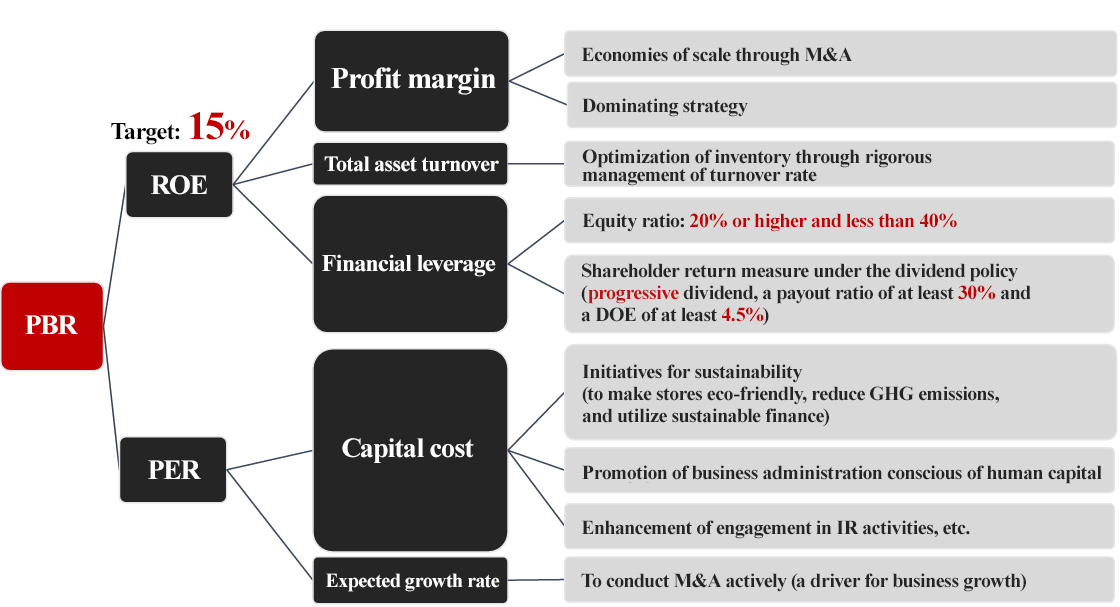
The company is implementing the following measures from the perspective of profit margin, total asset turnover, financial leverage, capital cost, and expected growth rate.
 |
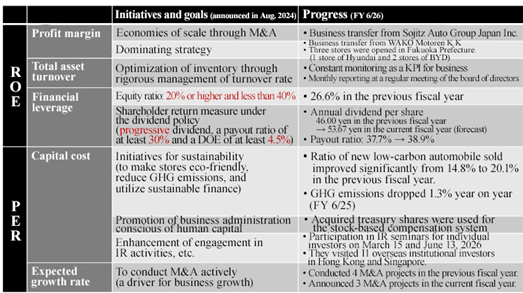 |
As a financial strategy, they aim to achieve an ROE of 15%, by “improving profit margin” with the advantage of scale and dominating strategy based on M&A, “improving total asset turnover” by rationalizing inventory through the thoroughgoing management of turnover rate, and “improving financial leverage” by setting the optimal capital composition (equity rati over 20% and less than 40%) and returning profit to shareholders.
As a result, the company will be able to achieve ROE well above the cost of shareholders' equity of 5.49% over the long term. They will maintain the system for keeping ROE above the cost of shareholders’ equity stably regardless of beta value to maximize their corporate value (market capitalization).
Regarding shareholder returns, as stated in “2-4 Medium- to Long-term Shareholder Return Strategy,” they will strive to maintain and improve stable and consistent profit returns through progressive dividends with a target dividend payout ratio of 30% and a minimum DOE of 4.5%.
In addition, the company is committed to strengthening shareholder returns through the flexible acquisition of treasury shares and improving corporate value through the introduction of various equity-based initiatives.
In terms of IR, the company intends to hold the general meeting of shareholders, build a forum for interaction with shareholders, both individual shareholders and institutional investors (inside and outside Japan), with the goal of promoting two-way communication by the management.
3. Growth Strategy
Three strategies promote the company's growth: "multi-brand strategy," "dominant strategy," and "M&A strategy."
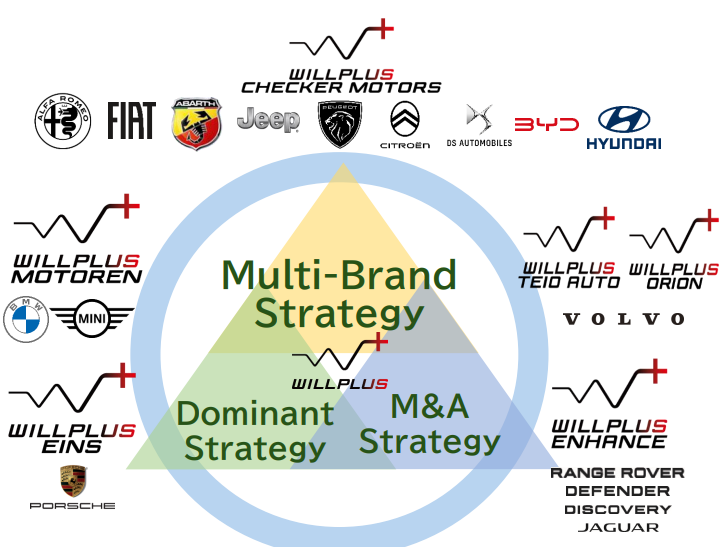
(From the reference material of the company)
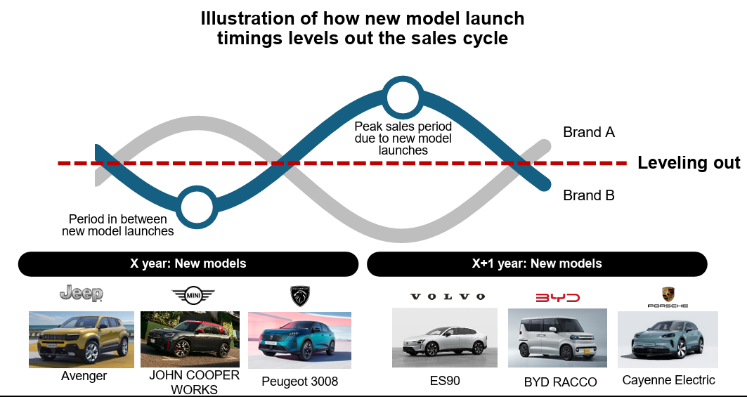
[3-1 Multi-brand strategy: Expansion of earnings and leveling of the sales cycle]
By handling multiple brands without relying on a specific brand, the company aims to even out the impact of the sales cycle caused by differences in the timing of new model launches among brands.
The company currently handles 17 brands and aims to expand the number of brands through M&A strategies.
(From the reference material of the company)
[3-2 Dominant strategy: Increase the market share and maximize profit in the same trade area]
The company is opening new stores in cities with a population of 1 million and surrounding cities, and regional core cities with a population exceeding 400,000 as specified areas in order to increase its market share by attracting customers in the same trade area, improve productivity through efficient personnel allocation among stores, and maximize profit.
Currently, the company focuses on Tokyo, Kanagawa, Saitama, and Kyushu, which are Japan's top markets in terms of new car registrations and ownership of imported cars (passenger cars), but it is also aiming to expand into other areas through the M&A strategy.
[3-3 M&A Strategy: Speed Up]
M&A is an important measure for quickly entering new areas, acquiring new brands (multi-brand strategy), and expanding the market share of existing brands. Following the acquisition of a huge number of stores, trade areas, and new brands via M&A, the company has been extending its business by building additional stores in neighboring regions to complement its trade areas.
There are many brands that the company targets but does not handle, such as Mercedes-Benz, Volkswagen, and Audi, and there is a tremendous opportunity for growth through the M&A acquisition of additional brands.
Aside from direct approaches from the company to the target companies and direct contact from the target companies back to the company, the company searches out deals through introductions from importers, financial institutions, and M&A brokerage firms.
The company will carry out due diligence and only engage in negotiations with those agreements that satisfy the company's investment recovery requirements following internal discussions that focus on prospects for future development and synergies.
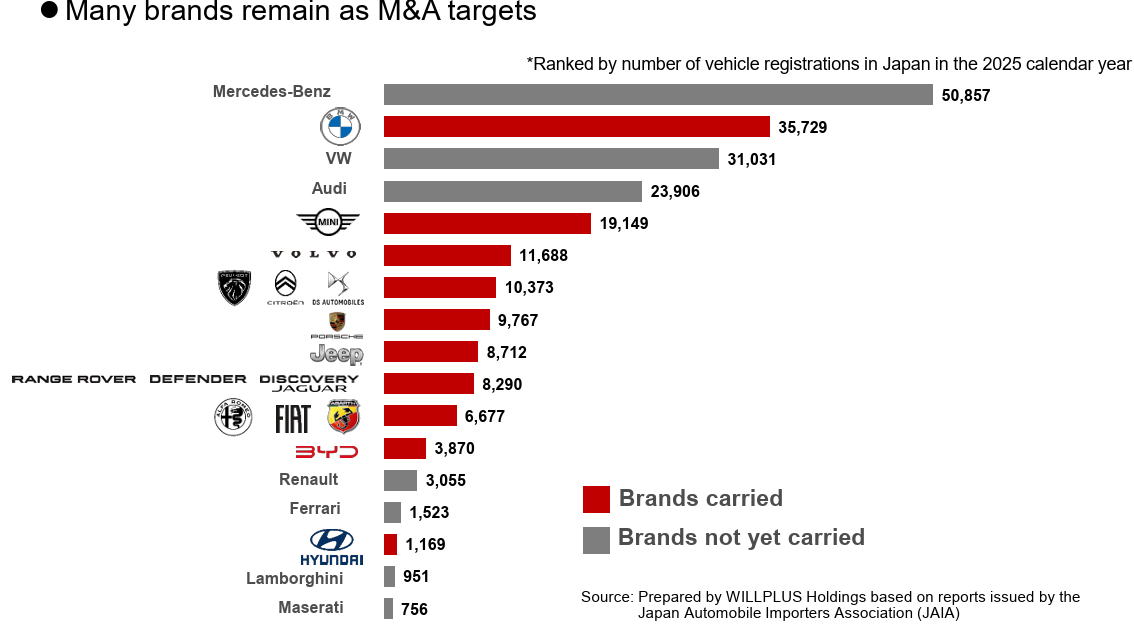
(From the reference material of the company)
Since their founding in October 2007, WILLPLUS Holdings has implemented 13 projects of M&A (*Excluding the ones in less than three fiscal years in the recent past). They have achieved profitability in all these projects by injecting their know-how, etc. in addition to opening new stores and making investments in stores, including relocation and renovation, and the high level of their PMI capability is attracting attention.
4. Fiscal Year ended June 2026 Earnings Results
[4-1 Overview of Financial Results]
| FY 6/25 | Ratio to sales | FY 6/26 | Ratio to sales | YoY | Compared with revised forecast |
Sales | 88,614 | 100.0% | 96,839 | 100.0% | +9.3% | +5.1% |
Gross Profit | 12,432 | 14.0% | 13,135 | 13.6% | +5.7% | - |
SG&A | 10,582 | 11.9% | 11,708 | 12.1% | +10.6% | - |
Operating Income | 1,849 | 2.1% | 1,426 | 1.5% | -22.9% | +1.9% |
Ordinary Income | 1,897 | 2.1% | 1,427 | 1.5% | -24.8% | +0.0% |
Net Income | 1,443 | 1.6% | 1,108 | 1.1% | -23.2% | -1.4% |
*Unit: million yen. Net income is net income attributable to owners of the parent. The comparison with the revised forecast means the comparison with the forecast announced in May 2026.
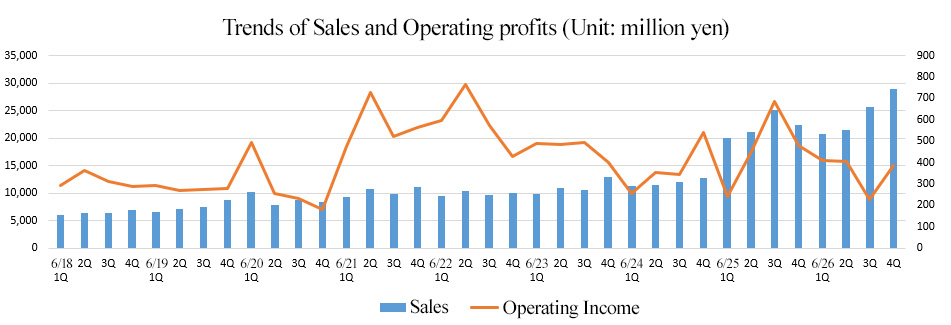
Sales increased, but profit decreased.
Sales grew 9.3% year on year to 96,839 million yen. Despite the harsh business environment, the stores that joined the Willplus Group in the previous fiscal year drove sales. The auto auction sales in the used car export-related business exceeded the forecast. They enhanced sales while putting importance on merchandise turnover.
Operating income dropped 22.9% year on year to 1,426 million yen, due to the sluggish sales of new cars and the decline in profitability of used cars in the imported vehicle dealer business, the augmentation of costs due to the increase of stores, the stagnant sales of major models, the rise in procurement costs, the congestion and cost augmentation in maritime transportation in the used car export-related business. Sales and operating income exceeded the revised forecasts announced in May 2026.
[4-2 Market Environment]
The number of registered new cars (passenger cars) in Japan decreased 2.7% from the previous fiscal year to 2.544 million. On the other hand, the number of registered new cars (passenger cars) made by non-Japanese makers increased 1.4% to 237,000. It was favorable in the first half of the year, but declined at the beginning of the year, showed a year-on-year decrease, and the year-on-year increase in the annual total was slight.
The number of registered new cars of the brands they deal in, too, decreased from the same month of the previous year for 10 months in a row since October 2025, and the annual total decreased 5.3% from the previous fiscal year, falling below the average in the market.
While the results of most brands declined from the previous year, Volvo expanded its market share, showing a good performance. The vehicles of BYD and Hyundai, too, increased significantly.
[4-3 Trend of each business and sales by product category]
◎ Trend of each business
| FY 6/25 | Composition ratio | FY 6/26 | Composition ratio | YoY |
Sales |
|
|
|
|
|
Imported vehicle dealer business | 54,230 | 61.2% | 58,110 | 60.0% | +7.2% |
Used car export-related business | 34,383 | 38.8% | 38,728 | 40.0% | +12.6% |
Total | 88,614 | 100.0% | 96,839 | 100.0% | +9.3% |
Segment profit |
|
|
|
|
|
Imported vehicle dealer business | 2,515 | 4.6% | 2,243 | 3.9% | -10.8% |
Used car export-related business | 433 | 1.3% | 376 | 1.0% | -13.3% |
Adjustment | -1,100 | - | -1,192 | - | - |
Total | 1,849 | 2.1% | 1,426 | 1.5% | -22.9% |
*Unit: million yen. The composition ratio of profit is the profit margin on sales.
◎ Sales by product category
(FY6/26)
| Import (*1) | YoY | Export (*2) | YoY | Total (*3) | YoY |
New cars | 24,760 | -1.7% | - | - | 24,760 | -1.7% |
Used cars (Japan) | 16,872 | +13.6% | - | - | 16,872 | +12.0% |
(Overseas) | - | - | 10,208 | -21.9% | 10,208 | -21.9% |
Used car total | 16,872 | +13.6% | 10,208 | -23.2% | 27,081 | -3.8% |
Auto auction sales | 5,834 | +11.7% | 28,501 | +35.3% | 34,335 | +30.6% |
Subtotal of sales of cars | 47,468 | +4.9% | 38,709 | +12.7% | 86,178 | +8.2% |
Car maintenance | 9,821 | +19.8% | - | - | 9,821 | +19.8% |
Other | 821 | +8.3% | 19 | -13.6% | 840 | +7.7% |
Total | 58,110 | +7.2% | 38,728 | +12.6% | 96,839 | +9.3% |
*Unit: million yen. Import (*1) represents imported vehicle dealer business, Export (*2) represents used car export-related business, Total (*3) represents Group total.
<Imported vehicle dealer business>
*New Car Sales
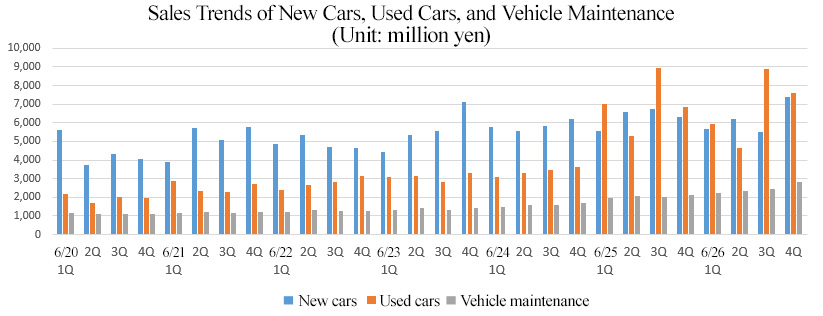
Sales decreased 1.7% year on year to 24,760 million yen.
The brands they deal in and stores increased through M&A, but the year-on-year increase in the number of vehicles sold increased was slight. The sales of brands handling expensive vehicles were sluggish, as there were no signs of recovery in the market environment.
*Used Car Sales
Sales grew 13.6% year on year to 16,872 million yen.
They surely seized selling opportunities, by securing trade-in cars, sharing inventory information among stores, cementing the cooperation in sale, improving the sales network by taking over businesses, and so on. The number of used cars sold increased significantly from the previous fiscal year, as they promoted sales while putting importance on the turnover rate of used cars.
*Recurring-revenue business
Sales from vehicle maintenance increased 19.8% year on year 9,821 million yen. The results were favorable, as the number of car maintenance shops increased, the service network expanded, the clients for continuous transactions increased, and so on.
The non-life insurance agency business was significantly affected by the revision to the system for agency commissions, although they responded to the revision, and the increase in the revenue from insurance commissions increased 8.7% from the previous fiscal year, as small as 477 million yen. Other sales, including the revenue from insurance commissions, increased 8.2% from the previous fiscal year to 821 million yen.
<Used car export-related business>
The Malaysian economy, our primary export market, continues to show signs of expansion, and the weak yen against the Malaysian ringgit has also been a tailwind for our export business.
The overseas sales in the first half of the fiscal year dropped significantly year on year, due to such factors as the country reaching its import quota for 2025 by early August, coupled with the beginning of a period of declining demand, and sluggish sales of models that have been considered by the company as core products. The sales in the second half of the fiscal year, too, declined year on year. As a result, annual overseas sales were 10,208 million yen, down 21.9% year on year.
The auto auction sales increased 35.3% year on year to 28,501 million yen, showing a healthy performance, as they enhanced sales while putting importance on the turnover rate of products.
[4-4 Financial Standing and Cash Flow]
◎ Main Balance Sheet
| End of June 2025 | End of June 2026 | Increase/ Decrease |
| End of June 2025 | End of June 2026 | Increase/ Decrease |
Current Assets | 26,675 | 31,543 | +4,867 | Current Liabilities | 18,051 | 24,408 | +6,357 |
Cash and Deposits | 8,245 | 10,475 | +2,229 | Payables | 4,182 | 4,370 | +188 |
Inventories | 13,276 | 15,524 | +2,247 | ST Borrowings | 8,100 | 13,200 | +5,100 |
Noncurrent Assets | 10,555 | 12,374 | +1,818 | Noncurrent Liabilities | 6,975 | 6,615 | -360 |
Tangible Assets | 8,865 | 10,288 | +1,423 | LT Borrowings | 6,171 | 5,664 | -506 |
Buildings and Structures (net amount) | 4,325 | 4,582 | +256 | Total Liabilities | 25,026 | 31,023 | +5,997 |
Intangible Assets | 266 | 415 | +149 | Net Assets | 12,204 | 12,893 | +688 |
Investment, Others | 1,424 | 1,670 | +246 | Retained Earnings | 10,167 | 10,837 | +670 |
Total Assets | 37,231 | 43,917 | +6,686 | Total Liabilities and Net Assets | 37,231 | 43,917 | +6,686 |
*Unit: million yen.
Total assets increased 6.6 billion yen from the end of the previous fiscal year, due to the increase of cash & deposits and vehicles in stock (inventory assets) at stores that joined the Willplus Group through M&A.
Total liabilities augmented 5.9 billion yen year on year, due to the increase in short-term debt caused by M&A.
Net assets increased 600 million yen year on year, primarily due to an increase in retained earnings.
As a result, capital-to-asset ratio declined 2.4 points from the end of the previous fiscal year to 26.6%
◎CF
| FY 6/25 | FY 6/26 | Increase/ Decrease |
Operating CF | -1,303 | 764 | +2,067 |
Investing CF | -545 | -3,007 | -2,462 |
Free CF | -1,848 | -2,243 | -395 |
Financing CF | 2,578 | 4,454 | +1,876 |
Cash and Equivalents | 8,234 | 10,445 | +2,211 |
*Unit: million yen.
While the cash flow from operating activities turned positive due to the augmentation of depreciation, the decrease in gain on negative goodwill, etc., the cash outflow from investment activities increased due to the expenditure for taking over business, etc. The deficit in free cash flow augmented.
The cash inflow from financial activities increased due to the rise in short-term debt, etc. The cash position improved.
[4-5 Topics]
(1) Continuous implementation of M&A
The company actively conducted M&A, which is a key pillar of the growth strategy.
① Acquisition of the authorized Volvo dealer business (in Urawa and Omiya)
In August 2026, the company acquired the “Authorized Volvo Dealer Business” operated by First Auto Co., Ltd.
The company acquired the business at 150 million yen. The acquired business generated a revenue of about 2.7 billion yen (as the actual result yielded in the fiscal year ended March 2026).
This has allowed the company to make its first entry into the Kanto region as a Volvo dealer. It has expanded its store network in Saitama Prefecture by acquiring two stores operated by First Auto Co., Ltd., “Volvo Car Urawa” and “Volvo Car Omiya.”
② Acquisition of the authorized Land Rover retailer business (in Setagaya and Meguro)
In August 2026, the company acquired part of the “Authorized Land Rover Retailer Business” operated by BC Japan Co., Ltd.
The company acquired the business at about 1.6 billion yen. The revenue generated by the acquired business was about 6.4 billion yen (as the actual result yielded in the fiscal year ended September 2025).
The company acquired the stores operated by BC Japan Co., Ltd., which are “Land Rover Setagaya” and “Land Rover Setagaya Service Center.” It also obtained the business rights of stores based in some areas of Tokyo and Kanagawa Prefectures (the employees and customers), including “Land Rover Meguro” (*the company has not acquired the store of “Land Rover Meguro”).
It has increased the number of its Land Rover dealerships in the Tokyo metropolitan area.
③ Acquisition of the shares in OGUNI Co., Ltd. and PHA Co., Ltd. (as subsidiaries)
In July 2026, the company acquired the shares in OGUNI Co., Ltd, which operates the “Authorized Volvo Dealer Business,” and PHA Co., Ltd., which operates the “Authorized Porche Dealer Business” (both companies are based in Himeji City, Hyogo Prefecture).
The company acquired the shares at 1 yen. The acquired companies generated a revenue of about 2.9 billion yen in total (as the actual result yielded in the fiscal year ended July 2026).
The acquisition of the stores operated by the OGUNI Group, which are “Volvo Car Himeji,” “Volvo Selekt Himeji,” and “Porche Center Himeji,” has allowed the company to operate its first Porche dealership in the Kansai region and expand its Volvo dealership network. Porche Center Himeji is the company’s third Porche dealership in Japan.
④ Acquisition of the business of Sojitz Auto Group Japan Inc.
In April 2026, the company acquired the “Authorized Volvo Dealer Business” operated by Sojitz Auto Group Japan Inc.
The company acquired the business at 1,250 million yen. The revenue generated by the acquired business stood at about 3.4 billion yen (as the actual result yielded in the fiscal year ended March 2025).
By acquiring the five stores operated by Sojitz Auto Group Japan —“Volvo Car Nishinomiya,” “Volvo Car Takamatsu,” “Volvo Select Tokushima/Service,” “Volvo Select Matsuyama/Service,” and “Volvo Gallery Matsuyama”—the company has established its first business presence in the Kansai and Shikoku regions. Following their success in the Kyushu region, they have established a dominant market position in the Shikoku region as well. It has gained a dominant position for the first time in the Kansai and Shikoku area. It has dominated the market in the Shikoku area as an exclusive authorized Volvo car dealer.
⑤ Acquisition of the business of Wako Motoren K.K
In January 2026, the company acquired the “Authorized BMW Dealer Business” operated by Wako Motoren K.K.
The company acquired the business at about 1,360 million yen. The acquired business generated a revenue of about 5.1 billion yen (as the actual result yielded in the fiscal year ended December 2024).
The company acquired "BMW Koshigaya, BPS Koshigaya, BMW Ageo, and BPS Kasukabe"—all operated by Wako Motoren—marking its first entry into Saitama Prefecture. The company opened its first BMW stores in the Tokyo metropolitan area and strengthened the group’s network.
⑥Acquisition of the business of GRAND CIEL SEKISHO Co., Ltd.
In January 2026, the company acquired “part of the authorized Peugeot dealer business” operated by GRAND CIEL SEKISHO Co., Ltd.
The company acquired the business at about 140 million yen. The acquired business generated a revenue of 290 million yen (in the fiscal year ended March 2025).
Through the acquisition of "Peugeot Koriyama," which is currently operated by GRAND CIEL SEKISHO Co., Ltd., the company established its second business location in Fukushima Prefecture, thereby strengthened its business structure in the Tohoku region. This will be the third Peugeot dealership to open.
⑦ Acquisition of the business of Sanyo Automobiles Co., Ltd.
In January 2026, the company acquired part of the “authorized Jeep dealer business” operated by Sanyo Automobiles Co., Ltd.
The company acquired the business at 36 million yen. The revenue generated by the acquired business amounted to about 300 million yen (as the actual result yielded in the fiscal year ended December 2024).
They have acquired “Jeep Oita,” operated by Sanyo Automobiles Co., Ltd., and established their second business location in Oita Prefecture. This move further strengthens their business structure in the Kyushu region. Jeep Oita, the only authorized Jeep dealer in the prefecture, aims to expand their dominant market area. This marks the opening of their ninth Jeep dealership.
(2) Status of store openings
In July 2025, the company opened “BYD AUTO Fukuoka” and “Hyundai Citystore Fukuoka” simultaneously in Fukuoka City, Fukuoka Prefecture. The two stores are adjacent to each other, which enables customers to test-drive the electric vehicles of the two brands.
It opened BYD AUTO Kitakyushu in Kitakyushu City, Fukuoka Prefecture, in August 2026. “BYD AUTO Kitakyushu” is the company’s third BYD dealership in Fukuoka Prefecture.
(3) Business Transfer
In January 2026, the BYD and Hyundai brand operations previously managed by Willplus Enhance Co., Ltd. were transferred to Willplus Checker Motors Co., Ltd.
5. Fiscal Year ending June 2026 Earnings Forecasts
[5-1 Earnings Forecast]
| FY6/26 | Ratio to Sales | FY6/27 (Est) | Ratio to Sales | YoY |
Sales | 96,839 | 100.0% | 116,416 | 100.0% | +20.2% |
Operating Income | 1,426 | 1.5% | 2,255 | 1.9% | +58.1% |
Ordinary Income | 1,427 | 1.5% | 2,075 | 1.8% | +45.4% |
Net Income | 1,108 | 1.1% | 1,256 | 1.1% | +13.3% |
*Unit: million yen. Estimates are those of the company.
Sales and profits are expected to increase. Sales are forecast to hit a record high.
Sales are projected to increase 20.2% year on year to 116,416 million yen and operating income is forecast to rise 58.1% year on year to 2,255 million yen.
Only the already announced M&A is taken into account for the earnings forecast. In the fiscal year ending June 2027, too, they will keep conducting M&A, but operating income margin is expected to slowly improve from 1.5% to 1.9%, as “the effect of improvement through post-merger integration (PMI)” will offset “the augmentation of costs through new M&A.”
They plan to pay dividends totaling 53.67 yen/share, up 7.67 yen/share from the previous fiscal year. The expected payout ratio is 38.9%.
[5-2 Initiatives]
Considering the current fiscal year to be a year in which the company earns revenue based on its enhanced capabilities as an organization, the company aims to secure profitability by recovering the earning capacity of its existing stores and promoting post-merger integration (PMI) of new stores through M&A.
The company will strengthen its initiatives relating to human capital-oriented business administration under which the value of human resources, which are the most important assets of the corporate group, is maximized, it will make investments that are necessary for developing personnel and improving its capabilities as an organization. It will proactively reduce unnecessary and inefficient costs by continuously examining the necessity and cost-effectiveness of various costs and enhance its business administration base for making it possible to allocate its business resources to growing domains and highly profitable businesses in an optimum manner.
◎ Priority policies in each segment
(1) Imported vehicle dealer business
The company will strive to increase profitability and generate synergy as swiftly as possible regarding the stores it acquired through M&A in the fiscal year ended June 2026, and it expects that the business results of OGUNI Co., Ltd. and WILLPLUS OGUNI Co., Ltd., whose shares were acquired in July 2026, will contribute to its business performance throughout the year.
In addition, the company will expand the business scale and increase profitability by enriching its sales basis and service network through other M&A projects it proactively conducted. In the vehicle maintenance and non-life insurance agency businesses that are recurring-revenue businesses, the company will endeavor to establish a more stable and stronger revenue base through further enhancement of its continuous contact and relationship of trust with each one of its clients.
(2) Used car export-related business
While keeping a close eye on the economic trends, exchange rates, and how the import licensing system is operated in Malaysia, one of the company’s major export partners, the company will engage in agile procurement and sales activities according to the demand in the country. It will aim to improve profitability through enhancement of the auto auction sales in Japan and streamlining of the business bases and administrative functions with a focus on the inventory turnover.
6. Conclusions
They actively conduct M&A, which is a pillar of growth strategies. As mentioned in “4. Fiscal Year ended June 2026 Earnings Results [4-5 Topics],” they took over businesses and acquired shares in 7 projects from January to August 2026.
The prices of new cars remain high due to the yen depreciation and the inflation. This leads to the augmentation of costs for company-owned vehicles and depreciation, the decrease of visitors to stores, and the worsening of cash management due to the increases in inventory and working capital, weighing on the management of small and medium-sized automobile dealers. In addition, it seems that M&A targeting mainly small and medium-sized dealers whose management bases are weak is accelerating, as people are putting more importance on the response to climate change, high-end automobile makers demand the capital integration among dealers, and imported car dealers are faced with the difficulty in finding successors.
Since Willplus Holdings was established in October 2007, they have conducted 13 M&A projects, excluding the ones in less than three fiscal years in the recent past, and all of acquired businesses succeeded in earning profit. Accordingly, their “business revitalization capability” can be said to be remarkable.
Going forward, the key point will be how PMI can be conducted speedily. They will carry out M&A also in the fiscal year ending June 2027. Operating income margin is expected to improve slowly from 1.5% to 1.9%, thanks to “the improvement effect of PMI” offsetting “the augmentation of costs for new M&A.” Further improvement in profit margin is expected to lead to a rise in PBR through the improvement in ROE.
<Reference: Regarding Corporate Governance>
◎ Organization type, and the composition of directors and auditors
Organization type | Company with audit and supervisory committee |
Directors | 7 directors, including 4 outside directors (4 of which are independent executives) |
Audit committee members | 4 members, including 4 outside directors (4 of which are independent executives) |
◎ Corporate Governance Report
Last update date: September 30, 2026
<Basic Policy>
Our company’s basic approach on corporate governance is to establish a sound management system that can respond to rapid changes in society and is efficient and compliant with laws and regulations, for maximizing our corporate value. To achieve this, we continue to strive to ensure transparent management and appropriate and prompt disclosure, by strengthening our relationships with stakeholders and further enhancing management governance functions.
<Reasons for Non-compliance with the Principles of the Corporate Governance Code (Excerpts)>
Our company follows all principles of the Corporate Governance Code.
<Disclosure Based on the Principles of the Corporate Governance Code (Excerpts)>
■Principle 1-3: Fundamental Capital Policy
Our fundamental capital policy is to maintain an appropriate capital base, consistently achieve an ROE that exceeds our cost of capital, and enhance corporate value.
Detailed information regarding our efforts to manage the company with a focus on our cost of capital and share price is disclosed on our company website.
https://contents.xj-storage.jp/xcontents/AS01236/c344ad3a/f422/40ec/9afb/9d116046c9e6/140120250814541929.pdf
■ Principle 1-4 [Strategic Shareholding]
(1) Policies concerning strategic shareholding
Our company does not hold shares strategically. Unless such shareholding is necessary to maintain and strengthen relationships for capital tie-ups and collaboration with our business partners and it is determined that their business benefits are worth the risk and cost of capital from the medium/long-term perspective, we shall adhere to our company’s policy of not holding shares strategically.
(2) Review process concerning strategic shareholding, and criteria for exercising voting rights related to strategically held shares
If it is considered appropriate to hold shares strategically, we will establish a method to review the reasonableness of continued holding of such shares as well as specific criteria for the exercise of voting rights on such shareholding.
■ Supplementary Principle 2-4 ① [Ensuring Diversity in Appointment of Core Personnel, etc.]
< Our view on ensuring diversity >
Our company aims to provide an environment where every and each staff member can utilize their ability to the maximum extent, and our basic policy is to promote human resources based on individual ability, aptitude, achievements and motivation, regardless of gender, nationality and attributes.
<Voluntary and measurable targets for ensuring diversity>
Regarding ensuring the diversity of core human resources, we have set targets for the ratio of female directors and managers and the ratio of male employees who have taken childcare leave, which serve as indices for ensuring diversity. The targets and results for each category are shown in the chart below.
| Result in FY 6/26 | FY 6/30 (target) |
Ratio of female directors | 12.5% | 30.0% |
Ratio of female managers | 7.2% | 10.0% |
Ratio of male employees who have taken childcare leave | 56.5% | 50.0% |
*As of the date on which this report was submitted, the ratio of female directors was 14.3% (one out of seven directors).
We have not set concrete numerical targets for the promotion of foreigners to managerial positions as there are few employees of foreign nationality at our company, but we shall keep discussing the necessity of setting such targets for ensuring further diversity.
Furthermore, as the proportion of highly specialized and experienced mid-career recruits is high in our corporate group, mid-career recruits account for 98.1% of managers (as of the end of June 2026). We have therefore not set any targets for the ratio of mid-career recruits in managerial positions.
■ Supplementary Principle 3-1 ③ and Supplementary Principle 4-2 ② [Issues related to Sustainability]
Our company has formulated basic sustainability policies, and established a Sustainability Committee and a Risk Management Committee to strengthen our corporate group’s sustainability initiatives and proactive risk management platform, and to focus on expanding our business scope by promoting growth strategies, responding to technological innovations including EVs in the automotive industry, and promoting DX, in order to achieve a sustainable society and enhance corporate value through our corporate activities. Details concerning concrete activities centered on these committees and investments in human capital, etc. for elevating the corporate value in the medium/long term are disclosed in our financial results presentation materials, annual security reports, etc.
https://contents.xj-storage.jp/xcontents/AS01236/73a1773f/f10e/4676/be8e/00e6a0e3b739/140120250827548317.pdf
In addition, our efforts to address climate change issues are disclosed through CDP.
For details, please refer to the “Sustainability” section on our company website.
https://www.willplus.co.jp/sustainability/
■ Principle 5-1 [Policies concerning the establishment of a system to promote constructive dialogue with shareholders and the initiatives for it]
Our company believes that clearly explaining our management policies and growth strategies to shareholders and institutional investors and deepening their understanding through active and constructive dialogue (interviews) with them will contribute to enhancing our company’s medium/long-term corporate value.
Dialogue with shareholders and institutional investors is conducted reasonably through visits, office visits, telephone calls, etc. by representative directors and IR staff, with the IR Office of the Corporate Strategy Division as a point of contact. In addition to individual interviews, in order to provide opportunities for direct dialogue with many investors, our company holds financial results briefings for investors and analysts as well as briefings for individual investors at which representatives themselves give explanations, and uses such opportunities to promote mutual understanding between our company and investors. Furthermore, we broadly disseminate information by video streaming of the meetings or posting material on our website.
When engaging in dialogue, we take all necessary precautions to ensure that there is no leakage of unpublished important information.
This report is not intended for soliciting or promoting investment or offering advice on investment or the like, but for providing information. In addition, the information included in this report was obtained from sources considered reliable by our company, but our company does not guarantee the accuracy, integrity or appropriateness of information or opinions included in this report or take responsibility for any kinds of expenses, damage, or the like arising out of the use of this report or information included herein. All kinds of rights related to this report belong to our company. The contents, etc. of this report may be changed without notice. Please make an investment decision on your own judgment. Copyright(C) Investment Bridge Co., Ltd. All Rights Reserved. |